Your Mortgage Has a Back Office. Valon Raised $150 Million to Bring AI Into It.
Making a mortgage payment takes a few clicks. Behind that payment is a long list of jobs: updating the loan balance, accounting for interest, setting aside money for property taxes and insurance, and making sure the records match.
Valon is building software to handle that work—and putting AI agents inside it.
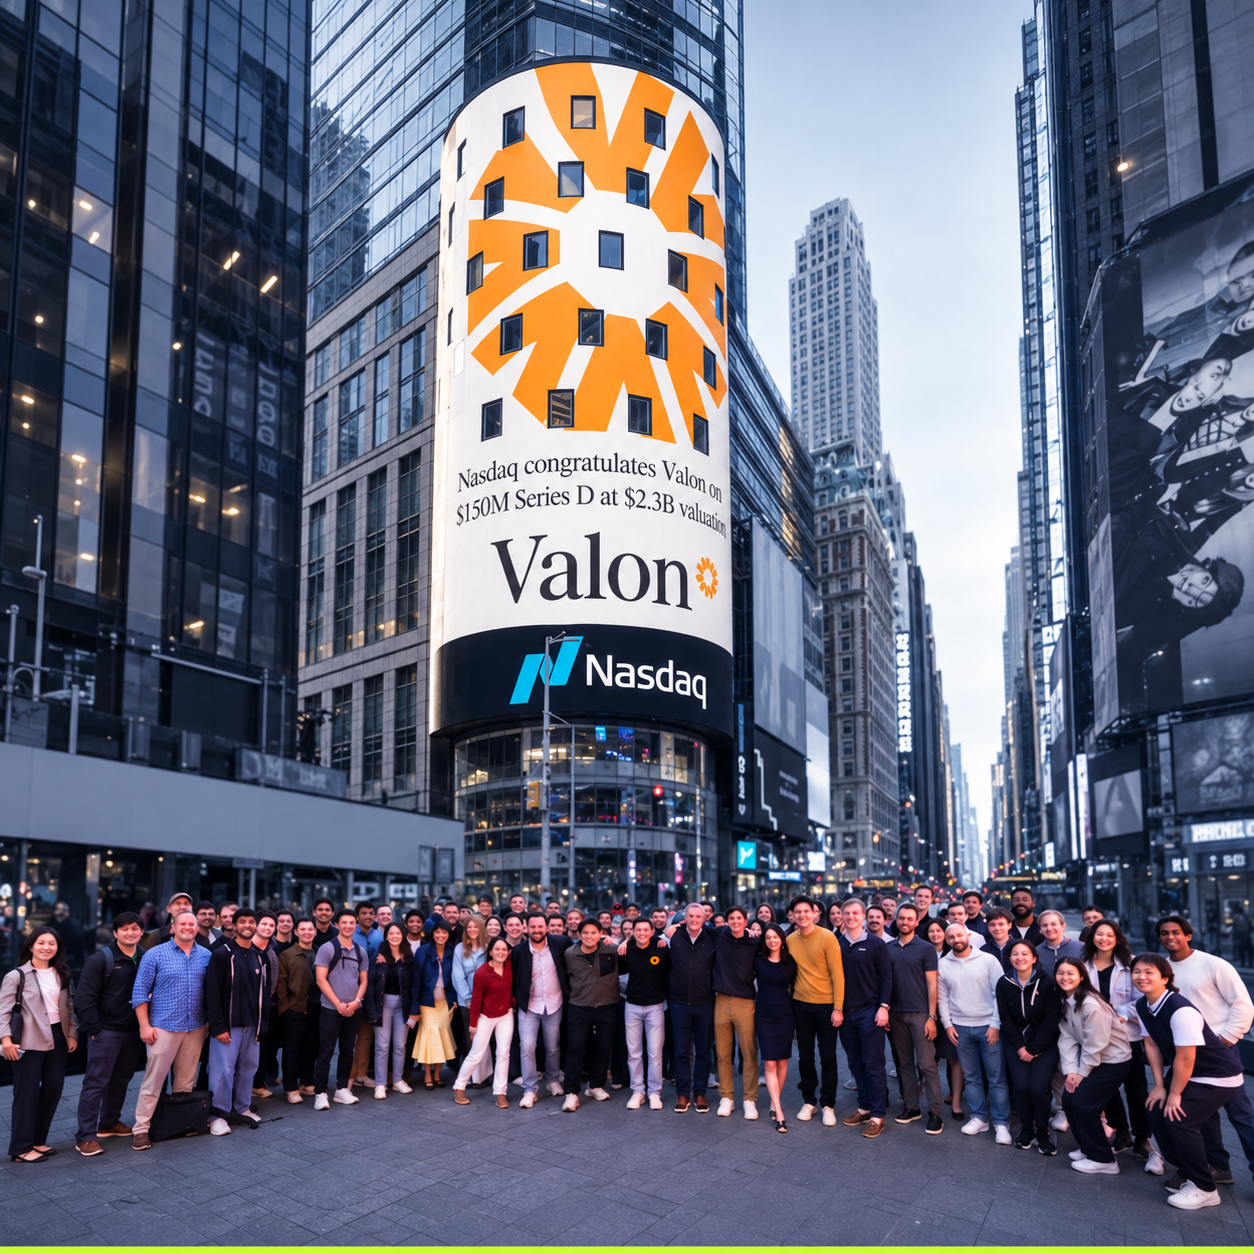
The company announced a $150 million Series D on October 5, valuing it at $2.3 billion. Ribbit Capital joined as a new investor, alongside returning backers including Andreessen Horowitz. The funding will support product development and the rollout of ValonOS to more mortgage companies.
Valon says companies responsible for one in six outstanding U.S. mortgages are under contract to use its platform. That is its contracted reach, rather than the number already running on the system.
Post from @valonView the original post on X↗
What Happens After You Get the Mortgage
The company that gives you a home loan is not always the company that manages it afterward.
That ongoing job is called mortgage servicing. It includes collecting monthly payments, maintaining records and helping borrowers when problems arise. It can continue for decades after the original loan closes.
Valon’s founders approached the problem by doing the work themselves. They built and operated a licensed mortgage servicer before selling their software to other companies. According to investor a16z, that business grew to manage more than 850,000 loans, representing roughly $196 billion in unpaid principal.
In August 2026, Carrington acquired Valon’s servicing business and adopted ValonOS. Valon Technologies retained the software business. Its customers include Carrington, ServiceMac and Rithm Capital’s Newrez.
That experience matters to the company’s pitch: it developed the software while dealing with the same payments, records and borrower questions its customers face.
What the AI Actually Does
Valon says its agents handle work including homeowner emails, payment allocation and escrow analysis—checking the money collected to cover property taxes and insurance.
"The aim is to connect those tasks to a shared loan record."
If a borrower asks about a payment, the system needs the relevant transaction history. If a document changes something about the account, the right team needs to see it. Moving between disconnected systems makes that work harder.
ValonOS brings loan information, financial activity and task tracking into one platform. Valon says its AI operates within existing workflows and controls, while employees focus on exceptions and decisions requiring judgment.
For homeowners, the potential benefit is less time spent chasing answers or correcting account problems. Whether the rollout delivers that improvement will matter more than how many tasks an agent can complete.
There Is Already a Blockchain Connection
Valon also has a direct connection to blockchain-based lending through its partnership with Figure.
In a public explanation of the partnership, Valon said Figure uses ValonOS to service loans originated using blockchain technology. The companies also published a joint discussion of their work in February, months before this week’s funding announcement.
That connects two stages of lending: creating and financing a loan, then managing it as the borrower repays.
It also helps explain why better servicing belongs in the digital finance conversation. A loan still needs accurate records, payment handling and customer support, whatever technology was used to create it.
The Figure relationship does not mean all mortgages contracted to use ValonOS are onchain. It is a specific example of Valon’s software supporting blockchain-originated loans.
Post from @valonView the original post on X↗
The Same Trust Question, Closer to Home
Today’s Blockster opinion piece by t54 co-founder Chandler Fang asks what must happen before an AI agent can safely act with someone’s money: establish its authority, limit what it can do and keep evidence of its actions.
Mortgage servicing brings that question into an everyday setting.
An agent working on a home loan needs the correct records and clear permissions. Staff also need to understand what happened if a borrower challenges an action.
Valon says its system records who acted, when, the approval involved and the underlying information. Its agents work under the servicing team’s permissions, and the servicer retains responsibility for decisions.
That makes the next phase of the rollout worth watching. As more mortgage companies move onto ValonOS, the test will be practical: accurate payments, clearer answers and fewer problems for the people paying off their homes.
Reporting by Lidia Yadlos